No One Taught Him About Money, So This Teacher Taught Himself
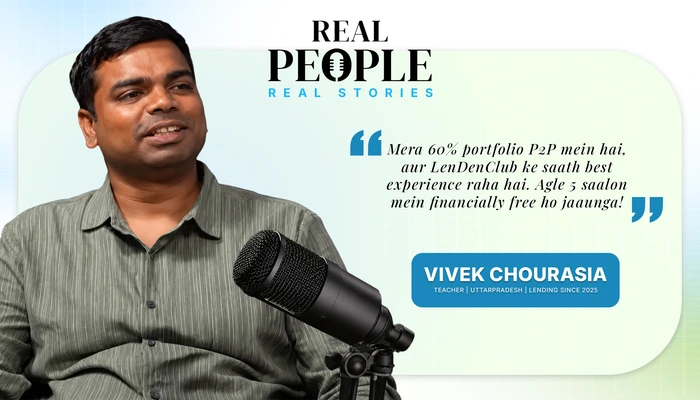
Vivek Chourasia

Welcome to the Real People, Real Stories blog, where every post spotlights a lender who has shared their experiences with us. In this episode, we spotlight a story of P2P lending in India. In Episode 5 of Season 2, host Rajat chats with Vivek Kumar Chaurasia (LenDenClub user since 2025) about his experience as a lender, mistakes he has made, and more.

Vivek Kumar Chaurasia had earlier invested with an app by getting a bit of interest that came daily in his account in the form of some credit to his account. One day, the option stopped, and he noticed the amount returned to his account.

Most people would have just left it at that, but not Vivek. He was curious and dug deeper to answer one question: how does P2P lending work?

Here is his story, and what he has discovered about P2P lending in the process.

Who is Vivek Kumar Chaurasia?

Vivek Kumar Chaurasia hails from Balganj, a small town in Gorakhpur district, UP. He is a teacher by profession posted in the rural hinterlands of Siddharth Nagar district.

It was a common practice in his area to save money in the form of LIC policies. When he got employed, the old family agent also turned up to sell him policies. However, Vivek had other plans.

“Bhale hum pichhde area se hain, lekin hum thoda modern tareeke se chalenge.” (We may be from a backward area, but we’ll do things a little modern way.)

Before making any investment, he bought health and term insurance to ensure that any medical emergency does not make him broke. He then started with a monthly SIP and continued to educate himself.

How Did He Come Across P2P Lending?

He wanted some money to be in a more liquid form, and one of the options on another app seemed a good fit. However, he had no idea that he was getting exposed to P2P lending in India. After about six to eight months, the option was closed, and the money automatically transferred back to his account. Instead of leaving it at that, he went back to the app and saw a line indicating that it was P2P lending, and the money had been returned because the borrowers had failed to repay. He then went through the process of Googling and interacting with AI to understand how P2P lending worked in general.

How Does P2P Lending Work?

What he found out was simple. It is a platform that brings borrowers and lenders together. The former gets listed after going through a due diligence process, while the latter gets to choose whom to lend to based on certain risk factors. As the borrowers repay, the lenders get some portion of the principal and the interest rate.

It was nothing new for him because, in his village, it was common for people to give loans at a certain rate of interest. The only challenge was following up on the repayments because there was nobody to check on the creditworthiness of the borrower. With the platform, most of the work is automated, and some of the risk factors are considered.

“Jo mehnat humein karni hai, woh aap log already karke baithe hue hain.” (The effort we would have had to put in, you have already done.)

Why LenDenClub over Other Platforms?

Having done his background research on other platforms for P2P lending in India, he decided on LenDenClub.

“There is a regulatory cover, which gives me some sort of assurance. Although, I have to say that regulation does not necessarily mean that your borrower will repay, but at least there are some guidelines that need to be followed.” – Vivek Kumar Chaurasia.

Starting Small and Monitoring

He started small with a sum of ₹13,000 and monitored it for about a year before considering additional investments. His rationale was that before making any significant move, he needed to fully understand the art of P2P lending. At present, about 60% of his portfolio is in P2P lending.

“The Platform Does the Work”

With thousands of borrowers, his money seems to be in a lot of places at once. However, ask him for his one-sentence LenDenClub review, and he says with a smile, “I don’t do this, sir. Your platform does.”

The filters on the platform allow him to decide how much to lend to every borrower, starting from ₹250, apart from other risk factors like salary and age. This implies that a sum of ₹10,000 can go to about 40 borrowers. Additionally, his money is mostly on the platform, ready to be lent out within 24 hours.

Why Diversification Is Important to Him

Spreading small amounts of money to many borrowers is a sure way of minimizing P2P lending risks, according to Vivek Kumar Chaurasia.

“There is no assurance that a borrower who defaulted will not default again. Similarly, there is no assurance that a borrower who has always repaid on time will not default in the future.”

How P2P Lending Helps Meet Some Daily Needs

He has several repayments coming in on a daily basis. In the early years, he would use all the proceeds from the repayments, including the principal, to clear new loans. However, with the current income from P2P lending, he has chosen to save a portion for his daily expenses. In fact, in case of an emergency, he can even consider withholding some installments for a couple of months.

What Others Think about P2P Lending

When interacting with others about P2P lending, especially friends and family, Vivek Kumar Chaurasia realizes that most people do not take him seriously. They are people who still have faith in the traditional methods, and it will take time before they can consider P2P lending as an alternative.

His Advice about Getting Started with P2P Lending

His advice to anyone considering P2P lending is to invest a small portion of one’s income and watch it grow for at least a year or two.

“Study things deeply. Learn, and understand.” – Vivek Kumar Chaurasia.

Final Thoughts

Since no one taught Vivek Kumar Chaurasia about money, he has taught himself valuable lessons about P2P lending. In his LenDenClub review, the key takeaway is that the platform does most of the hard work, and he only has to focus on the things he understands. For anyone considering P2P lending in India, his Real People, Real Stories review will be a great starting point.

To check out his complete story, watch Episode 5 of Season 2 of Real People, Real Stories on LenDenClub’s YouTube channel.

Frequently asked questions

What is P2P lending in India?
P2P lending allows lenders to offer their surplus funds to individual borrowers on an online platform. These platforms need to be registered with the RBI as NBFC-P2Ps. In exchange for their services, lenders earn back the principal amount deposited plus the interest due from the borrower. However, as with any investment, there is a risk that the borrower fails to repay the loan.
How does P2P lending work?
A borrower submits an application on a P2P platform and goes through a screening process. Their application is then approved, and the loan details are posted on the site. At this point, lenders can choose how much to contribute to a particular loan and screen the borrower based on several factors, such as the minimum amount (starting at ₹250). Once the borrower repays, the lenders’ shares of the principal and interest are deposited back into their accounts and can either be withdrawn or reinvested.
What are the main P2P lending risks?
The main P2P lending risks emanate from the fact that the borrower is an individual, and not a business entity. As such, there is a high likelihood that they will default on the loan or only repay a fraction of the amount due. Additionally, the lenders do not have any guarantee on the returns, as they are dependent on the performance of the borrower. Regulation does not protect the lenders’ money, and while diversification reduces risk, it does not eliminate it entirely.
What is a good P2P lending investment strategy for beginners?
According to Vivek Kumar Chaurasia, a good P2P lending investment strategy entails putting aside a small amount of money and diversifying it across multiple borrowers. He advises beginners to put aside ₹13,000 and let it grow before considering additional investments. Every borrower is unique, and therefore, their ability to repay loans varies. As such, a lender should look at different risk factors associated with each borrower and only fund those that meet their personal risk appetite. It is also important for the lenders to consider how much money they are willing to invest.
What stands out in Vivek’s LenDenClub review?
For Vivek Kumar Chaurasia, the most appealing aspect of LenDenClub is the various filters that allow him to decide how much money to lend to each borrower, starting from ₹250. He can also specify the risk appetite, age, and occupation of the borrower. Furthermore, his money is mostly on the platform, ready to be lent out within 24 hours.
How should a first-time lender get started?
A first-time lender should research to understand how a P2P lending platform works, the screening process for borrowers, and the possible defaults that can affect their money. With that knowledge, they can make informed decisions on how much money to put on the platform. It is also important to start small and only invest amounts that one is willing to lose in case of a default. For instance, Vivek Kumar Chaurasia started with ₹13,000 and let it grow for a while before considering additional investments.

LenDenClub is India’s largest peer to peer lending platform which started operations in India in 2015. We have been helping lenders diversify their portfolio beyond traditional investment instruments ever since.


LenDenClub is India’s largest Peer to Peer (P2P) lending platform, operating since 2015. We are an RBI-registered NBFC-P2P connecting individual lenders with verified borrowers across India. Lenders on our platform earn interest income that is not market-linked, making P2P lending a complement to traditional financial instruments.

*Annualized Returns shown are historical on closed loan portfolios.

LenDenClub, operated by Innofin Solutions Pvt Ltd (ISPL) is registered as a peer-to-peer lending non-banking financial company (“NBFC-P2P”) with the Reserve Bank of India (“RBI”). The Reserve Bank of India does not accept any responsibility for the correctness of any of the statements or representations made or opinions expressed by Innofin Solutions Private Limited, and does not provide any assurance for repayment of the loans lent through its platform.
Registration Number: N-13.02267.

LenDenClub is an Intermediary under the provisions of the Information Technology Act, 2000 and virtually connects lenders and borrowers through its electronic platform via the website and/or mobile app.

The lending transaction is purely between lenders and borrowers at their own discretion, and LenDenClub does not assure loan fulfilment and/or lending simple interest. Also, the information provided on the platform is verified or checked on the best efforts basis without guaranteeing any accuracy of the data/information verification. Any lending decision taken by a lender on the basis of this information is at the discretion of the lender, and LenDenClub does not guarantee that the loan amount will be recovered from the borrower, fully or partially. The risk is entirely on the lender. LenDenClub will not be responsible for the full or partial loss of the principal and/or interest of lenders’ lending amounts.


*P2P lending is subject to risks. And lending decisions taken by a lender on the basis of this information are at the discretion of the lender, and LenDenClub does not guarantee that the loan amount will be recovered from the borrower.

CIN: U74999MH2015PTC266499.