Meet the Lender Who Runs His P2P Portfolio Like a Business
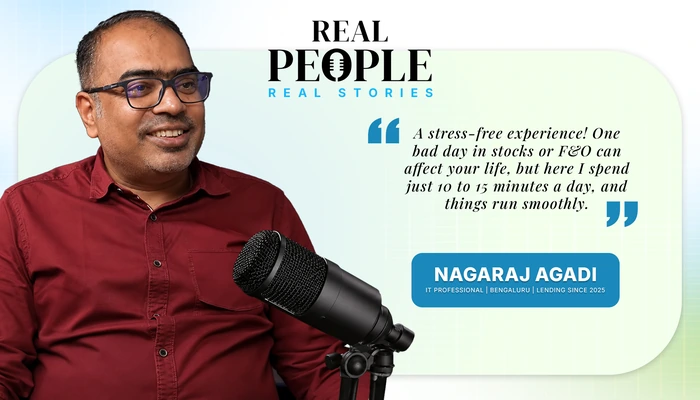
Most people think twice about diving into a new asset class, and rightly so. Is the platform regulated? How does cash get flowing? What happens if the borrower fails to repay? In Episode 6 of Real People, Real Stories (Season Two), host Rajat, from LenDenClub spoke with Mr. Agadi (lending since 11th August, 2025), a Bengaluru-based IT professional with over two decades of tenure at a multinational. What he shared was unusual: a P2P lending strategy that was like a small lending business, complete with his own dashboard, KPIs, and daily ledger.
Here’s what he built, what he learnt along the way, and what other lenders can take from it.
From fixed deposits to a wider mix
Starting small, and staying curious
His introduction to it was almost accidental. Reading about RBI regulation of P2P lending in India in a news article caught his eye, and he read up on how it had fared abroad and why regulation was important. As Rajat noted, RBI had issued Master Directions for NBFC-P2P platforms in 2017 and further tightened them in August 2024.
He started with ₹25,000, spread across loans of four to six months. After six months, the results were underwhelming. He had simply lent and waited.
As an IT professional, he did what he does best. He moved everything into a spreadsheet, built a dashboard, and did simulations. What would happen if repayments flowed directly back to work? What would happen if he spread his money wider?
The KPIs behind his P2P lending strategy
Most conversations with lenders are focused on individual borrowing, which bureau score, which tenure, will this pay back. Mr. Agadi built his own measures.
He interestingly calls “Relending velocity” the rate at which you re-lend repaid principal. To sum it up, as borrowers repay their loans, Mr. Agadi prefers to re-lend the principal received into new lending opportunities. He tracks this process closely to understand how efficiently he is deploying repayments across his portfolio. Principal relending ratio: the proportion of repaid principal he put back to work.
Once the simulations made sense, he expanded his lending book to roughly four times its original size and tracked these metrics from day one.
Rajat explained why this lens makes sense. LenDenClub approves around 3% of the loan applications it receives, each checked against more than 670 data points, from repayment history to average monthly balances. After that screening, predicting whether one borrower will repay is close to impossible for the individual. What the individual can control is how widely they spread their money, and how quickly they re-lend it.
The business lens: interest as revenue, NPAs as cost
Mr. Agadi borrowed an idea from a friend who runs a small business. He thinks of himself as the owner of a lending business, with the platform doing the groundwork of finding and assessing borrowers. In his model:
- The money he lends is his asset.
- Repaid principal is capital coming back.
- Interest received is revenue.
- NPAs and platform fees are costs.
- What is left is profit before tax.
He says his dashboard works like a daily ledger, helping him track profit and loss and maintain a balance sheet. When he receives the repayments, daily or even monthly; he makes a note of the principal and the interest received. The dashboard then shows him how much to re-lend and how much he can set aside. This roughly takes him about 10-15 minutes.
Understanding NPAs in P2P lending
Why diversification in P2P lending matters most
If there was one point both speakers returned to, it was this. The platform limits how much a lender can place in a single loan.In theory, there could be a lender who funds a borrower needing ₹10,000. Instead, the idea lends itself to splitting that ₹10,000 into 20 loans of ₹500.
Diversifying one’s P2P lending doesn’t eliminate risk, but it dampens the impact of defaults. Combined with the regularity of relending, this is the idea that informs Mr. Agadi’s approach. He likes the regular income stream that allows him to rebalance, paired with the observation that P2P lending is uncorrelated with the stock market. Instead of tracking daily F&O or equity swings, he views P2P lending as a safer slice of his portfolio.
What he'd tell other lenders
He acknowledges that many of his friends are sceptics. Some tried their hand at P2P lending, but abandoned the idea at the first stage of lending and waiting. His advice? Take a look at your portfolio at least once a week, just like any other asset class.
He also gave some brutally honest feedback. He’d like a clearer explanation of borrower screening, LenDenClub score and bureau score correlation, and more data on NPA trends and diversification in P2P lending. Rajat agreed that the explanation of P2P lending in India needs work. He added that the LDC score is based on those 670+ parameters, informing the assessment of new-to-credit borrowers without a bureau history.
Building your own P2P lending strategy
- You don’t need a dashboard of your own to borrow from his experience:
- Start with an amount that you’re comfortable with, and give it time.
- Diversify heavily into many loans, and not concentrated loans
- Relend the principal as and when it comes back to you, to keep the wheel moving
- Expect NPA, and measure P2P lending performance across a cycle, not the first few months
- Track a handful of simplistic metrics regularly
Final thoughts
Mr. Agadi described his journey as one from sceptic to convert. His story isn’t one that we’d recommend blindly following. It’s an illustration of how a thoughtful lender engages with P2P lending in India, informed by structure, patience and a healthy appreciation of risk.
If you’re considering embarking on a similar journey, remember Rajat’s final words of wisdom – diversify sufficiently, and don’t put all your eggs in a handful of loans. To truly understand the risks, refer to our explainer on the risks of P2P lending.
Frequently asked questions

Team LenDenClub
LenDenClub is India’s largest peer to peer lending platform which started operations in India in 2015. We have been helping lenders diversify their portfolio beyond traditional investment instruments ever since.