The One Simple Rule Behind Jay ’s P2P Lending

Jay Aditya

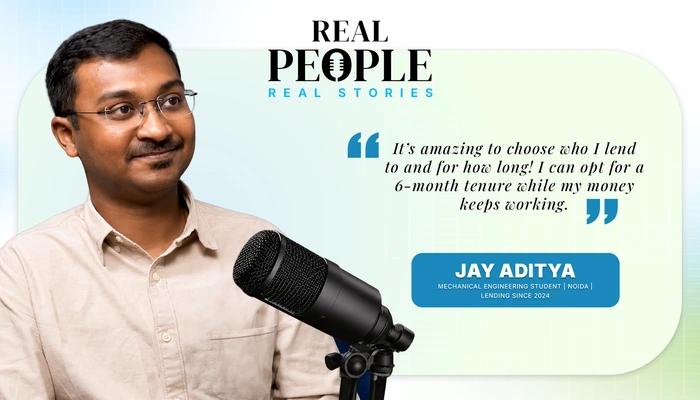
Welcome back to the Real People, Real Stories blog series, where every episode features a LenDenClub lender discussing their finances and sharing their story about P2P lending in India. In the second episode of the second season, the host, Rajat, invites Jay Aditya (LenDenClub user since 2024) from Noida to talk about his journey with LenDenClub, how he came to investing, and why his money went from being in one borrower’s hands to thousands of them.

When Jay told his mom that he would like to start investing, she didn’t quite believe he would get into it.

She thought fixed deposits and steady income streams were the only reliable ways to grow wealth, and she couldn’t understand why he would want to risk his money elsewhere.

“I told her it is not that difficult as long as you do some research before getting into it,”Jay says.

The same approach works for him in P2P lending, the space which currently makes up around five percent of his portfolio. This is the story of Jay’s P2P lending experience so far.

Who Is Jay Aditya?

Jay is a mechanical engineer by qualification and has spent the last couple of years working in a portfolio management company, educating himself on the do’s and don’ts of diversified investing. He describes his approach to stock market investments as “invest and forget,” because he only buys stocks of companies he finds interesting and follows their performance on a quarterly basis. He only reconsiders selling or buying when something changes with the company itself or its management practices.

Growing Up With Contrasting Money Beliefs at Home

Jay comes from a family of two – his parents never hid their beliefs and approaches about money from him, and he always had his own perspective to form. His mother was a firm believer in fixed deposits and only ventured into the stock market a little when he was already grown. His father, on the other hand, was much more comfortable with the volatile swings of the market. Their differing approaches created a lively and ever-present discussion about money that interested young Jay, who learned to formulate his own ideas while growing up.
“I started by practicing,”Jay says, and tells the story of his virtual investing in 2019. He followed through on his intentions in 2022, learning about the stock market mainly from YouTube and doing his own research. His previous job also helped him understand actual practices and methods in the industry.

Finding P2P Lending in India

Jay first heard about P2P lending in India during 2023, and he immediately knew it was something he would like to try. In 2024, he discovered LenDenClub, and the rest, as they say, is history. But what made him comfortable enough with the idea to get into it?
“I don’t really see it as anything different from other investment spaces,”Jay explains. He only sees P2P lending as a formalization of an informal practice that has existed and functioned for centuries – after all, giving money to someone with the promise of repayment with interest is a practice that has existed long before the invention of P2P lending platforms.
Regulation made the practice safer, in Jay’s opinion, and he finds the current level of security to be satisfactory. Of course, he also realizes that regulation does not eliminate default risk completely, and he lists default risk as one of the key P2P lending risks

What To Look For When Getting Into P2P Lending

“First and foremost,”Jay says when asked what someone new to the space should consider when choosing a P2P lending platform, “check if the platform has a sufficient number of borrowers listed. If they don’t, be careful.” Next, potential lenders should analyze the features and protections offered to lenders by the chosen platform. According to Jay, the entire process involves thorough research and understanding of the product.

“It Is All About Diversification”

When asked what interested him most about LenDenClub, Jay couldn’t say one particular thing. When asked about the number of borrowers he has on his P2P lending platform, he had to think about the number for a bit. “It feels unreal from the outside, but when you are in it, it is okay,” he finally says. According to him, it all comes down to P2P lending diversification.
“I think the key to P2P lending diversification is simple: the more the better, as long as you have the opportunity to do so.” He always lends in at least a hundred borrowers when he can, balancing short and long-term loans and varying the types of borrowers. Jay believes that spreading his money across multiple borrowers helps him manage the impact of individual defaults while building a more diversified P2P lending portfolio.

How to Choose Loans in P2P Lending

Jay enjoys the choice and opportunity that P2P lending gives him. He likes to choose who he lends to and for how long, so he always has some money that he knows is due to be repaid soon and can use it for other purposes if needed. He uses this approach to have more flexibility in his personal budget. In his current practice, he always lends new money to at least a hundred different borrowers, distributing it between short, medium, and long loans and varying the types of borrowers he lends to.
He used to do extensive research on different loan terms, comparing shorter and longer loans and how they affect his overall capital. He no longer does this because he found that the differences between them were smaller than he expected. Now, he lends in larger chunks of money, choosing one hundred different borrowers to spread his money between. He always leaves shorter loans for when he needs the money back, but he lends larger sums in longer loans to get a bigger interest rate.

How Withdrawals and Re-lending Work in P2P Lending

Jay keeps the money he earns from P2P lending in a separate account and withdraws from it whenever he needs to. When he uses lumpsum lending on the LenDenClub app, he waits for the lumpsum to get bigger before relending it. When he is the one choosing what to do with his earnings, he re-lend the money right away. He finds it helpful to track how much he has gotten back in P2P lending repayments, how much of it he has already re-lend, and how much he has left. He likes to know how much money he has put into the system so he can calculate how much more he needs to get to his desired level of earnings.

What Jay Would Say to Someone Thinking About Getting Into P2P Lending

For anyone thinking about trying P2P lending, Jay’s advice is to be patient. Before getting started, he took time to explore the platform and understand how it worked. His advice to beginners is to start with smaller amounts and consider adding more only when they feel comfortable with the process. According to Jay, this is how he built his P2P lending portfolio up, gradually increasing his lending as he got more comfortable with the idea. He also shares that for him, P2P lending had always been a part of a bigger picture, and the other, bigger part of his portfolio remained the same throughout the process.

What Wealth Means to Jay Aditya

When asked to describe wealth in one word at the end of the conversation, Jay says it is freedom and the ability to have more time for his family. He also gives all those who keep their savings in fixed deposits a challenge: put them to work instead of letting them gather dust. “At a later stage in life, the money would be working for you instead of you working for the money,” he says.

Conclusion

Jay has developed his own approach to P2P lending, but patience has always been an important part of it. Before putting in his money, he took the time to understand how everything worked. He started with smaller amounts and gradually added more as he became comfortable. For anyone looking to understand how to get started with P2P lending in India, Jay’s P2P lending experience offers a useful perspective.
Frequently asked questions

What is P2P lending in India?
Peer-to-peer (P2P) lending refers to the practice of giving money to individual borrowers through a P2P lending platform. These platforms operate under the RBI’s rules and are registered as NBFC-P2Ps. The platform lists the loans and screens the borrowers. On the other hand, lenders earn interest on the money the borrowers repay, including the principal amount. However, there is a possibility that a borrower may default, and lenders may fail to recover their money.
Is P2P lending regulated?
Yes, P2P lending in India is regulated. As explained above, the RBI oversees the operations of P2P lending companies, and the companies are registered with the RBI as NBFC-P2P. Although regulation helps set standards for these platforms, it does not ensure that lenders’ money is safe or that they will recover their money in case of default. Therefore, it is essential to understand the P2P lending risks before lending.
How do P2P lending repayments work?
In P2P lending, borrowers repay their loans in installments. Each installment consists of a portion of the principal amount and the interest due. Since each borrower’s repayment capacity varies, P2P lending repayments reach lenders at different times. Some lenders also re-lend their money into new loans right away to minimize the amount of money sitting idle.
Why is P2P lending diversification important?
Diversification is a strategy in which lenders spread their money among different borrowers to minimize default risk. Default risk refers to the possibility that a borrower fails to repay a loan. Ideally, lenders should diversify the amount as much as possible within their means.
What should you look for in a P2P lending platform?
If you are a first-time lender and want to find the right platform, there are several factors to consider. First, ensure that the company has a substantial number of borrowers on the platform. This is a crucial step when looking for a reliable platform, as the absence of a considerable number of borrowers may indicate a lack of credibility and raise questions about the legitimacy of the business. You might also want to investigate which organizations are registered with the RBI as NBFC-P2P and comprehend how the company evaluates the borrower’s creditworthiness and how repayments function.
How should a first-time lender get started with P2P lending?
First-time lenders should start with smaller amounts and take their time to understand how everything works.First-time lenders should evaluate a platform’s borrower assessment process, diversification features, repayment tracking and regulatory compliance to better understand how P2P lending works and how lending risks can be managed. Once a lender understands how P2P lending works, they can gradually increase their lending amount. In fact, this is what Jay did as he first lent small amounts and then increased his lending amount as he grew more comfortable with the concept.

LenDenClub is India’s largest peer to peer lending platform which started operations in India in 2015. We have been helping lenders diversify their portfolio beyond traditional investment instruments ever since.


LenDenClub is India’s largest Peer to Peer (P2P) lending platform, operating since 2015. We are an RBI-registered NBFC-P2P connecting individual lenders with verified borrowers across India. Lenders on our platform earn interest income that is not market-linked, making P2P lending a complement to traditional financial instruments.

*Annualized Returns shown are historical on closed loan portfolios.

LenDenClub, operated by Innofin Solutions Pvt Ltd (ISPL) is registered as a peer-to-peer lending non-banking financial company (“NBFC-P2P”) with the Reserve Bank of India (“RBI”). The Reserve Bank of India does not accept any responsibility for the correctness of any of the statements or representations made or opinions expressed by Innofin Solutions Private Limited, and does not provide any assurance for repayment of the loans lent through its platform.
Registration Number: N-13.02267.

LenDenClub is an Intermediary under the provisions of the Information Technology Act, 2000 and virtually connects lenders and borrowers through its electronic platform via the website and/or mobile app.

The lending transaction is purely between lenders and borrowers at their own discretion, and LenDenClub does not assure loan fulfilment and/or lending simple interest. Also, the information provided on the platform is verified or checked on the best efforts basis without guaranteeing any accuracy of the data/information verification. Any lending decision taken by a lender on the basis of this information is at the discretion of the lender, and LenDenClub does not guarantee that the loan amount will be recovered from the borrower, fully or partially. The risk is entirely on the lender. LenDenClub will not be responsible for the full or partial loss of the principal and/or interest of lenders’ lending amounts.


*P2P lending is subject to risks. And lending decisions taken by a lender on the basis of this information are at the discretion of the lender, and LenDenClub does not guarantee that the loan amount will be recovered from the borrower.

CIN: U74999MH2015PTC266499.